DLF Gardencity Enclave Phase 2
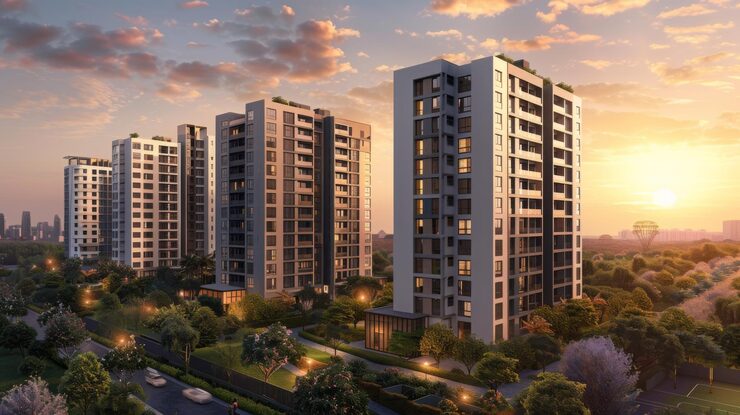
Four-storey floors in DLF's Gardencity area. Listing sites show October 2028 possession and about 291 homes. DLF's own homes page does not list it, so confirm availability with us before you plan a booking.
DLF's current launches start above ₹1 crore. Below are the nearest options, why DLF homes sit in a higher band, and how to plan a realistic stretch and get alerted.

If you are searching for DLF projects under 1 crore, here is the short answer. DLF's current launches focus on 3 BHK and larger homes, and none of its new, upcoming or under-construction projects has a published price below ₹1 crore. Knowing this now saves you time, and the sections below show the closest options.
This page is therefore a general guide. It does not claim that a cheap DLF home exists. Instead it shows you the closest options that we do know about, explains why the numbers look the way they do, and helps you plan what to do next if your ceiling really is one crore.
Everything on this site is independent information. We are not DLF Limited. Prices that come from listing portals are marked as such, and some may be old. Always ask for the latest written cost sheet before you decide anything.
None of these is verified below ₹1 crore. They are the lowest-priced or most budget-relevant DLF names we track, and some are sold out or have no price yet.
Four-storey floors in DLF's Gardencity area. Listing sites show October 2028 possession and about 291 homes. DLF's own homes page does not list it, so confirm availability with us before you plan a booking.
512 low-rise homes (stilt plus four floors) on 15.8 acres, about 10 km from Chandigarh, with views of the Kaushalya river and the Shivalik foothills. Launched in December 2023 and reported sold out, so ask us about resale. HRERA-PKL-PKL-524-2023.
HRERA lists two DLF projects here: The Valley Orchard for homes and The Valley Central, a commercial parcel (HRERA-PKL-PKL-626-2024). Ask us which one fits you.
Tricity is a search label, not one project. DLF's homes here include The Valley, Valley Gardens, Valley Orchard and Hyde Park in New Chandigarh. Tell us your budget and we will shortlist.
A 2022 report named Sriperumbudur as a planned DLF residential location. DLF has not published a plot project or TNRERA number here yet.
Send us your ceiling and city. We will tell you which of these is realistic and which is not.
Gardencity Enclave Phase 2 prices are undated aggregator figures. The Valley Orchard is reported sold out. Pinjore, Tri-city and Sriperumbudur have no published price.
DLF is known for premium housing. Its recent launches are mostly large 3 BHK and 4 BHK homes, penthouses, plots and shops in costly locations. A home built for that market rarely comes in under a crore. This is simply how the product is designed.
Land is the biggest reason. Sites in Gurugram, Mumbai and the Chandigarh area cost a lot per acre, and DLF often keeps low building density and big open areas. Fewer homes on each acre means each home carries more land cost.
Size matters too. A 3 BHK of about 1,500 sq ft needs a price of only around ₹6,700 per sq ft to cross one crore. Almost every DLF project we track is priced above that, so even the smallest homes cross the line.
Small, cheap launches such as 1 BHK or 2 BHK units usually come from other segments of the market. DLF has simply not announced such homes. If that changes, it will show up in this site's listings.
Here is a plain view of each option you may come across in a search for cheaper DLF homes.
Gardencity Enclave Phase 2 is the lowest quoted figure we found, at about ₹1.70 to ₹1.93 Cr on portals. It is 70 to 93 percent above a one-crore ceiling, so it needs a real stretch.
Launched in December 2023 around ₹9,000 per sq ft and reported sold out. Any purchase now would be resale, and the price is set by the owner.
These are search labels or early names. No price list is published, so we cannot say if anything sits below a crore.
No DLF launch of this type was found. A site that promises one at a low price should be checked with care.
Stretching a budget by 70 percent is not a small step. Before you try, work backwards from your income, not forwards from the home you like. Decide what monthly EMI you can pay for twenty years without stress.
As a plain example, a loan of ₹1 crore at 8.5 percent over 20 years has an EMI near ₹86,800 a month. This is only an illustration, not an offered rate. A loan of ₹1.5 crore would be near ₹1.30 lakh a month. Check this against your salary before you chase a bigger home.
Also count the cost that is not the loan. You will need a down payment, stamp duty, registration and other charges. Many buyers forget these until late, and then borrow more than they planned.
If the numbers do not work, that is a good result too. It tells you to widen the search to another price band, a smaller city, or a later date.
These numbers are examples to help you plan. They use 8.5 percent over 20 years. Your bank's rate and rules will differ.
| Loan amount | Approx. monthly EMI | Income to keep EMI near 40% |
|---|---|---|
| ₹50 lakh | About ₹43,400 | About ₹1.1 lakh a month |
| ₹1 crore | About ₹86,800 | About ₹2.2 lakh a month |
| ₹1.5 crore | About ₹1.30 lakh | About ₹3.3 lakh a month |
Example only, not an offered rate. EMI = loan × r × (1+r)^n ÷ ((1+r)^n − 1), where r is the monthly rate.
The price you see in an advertisement is rarely the price you pay. Under-construction homes usually add GST, and every home needs stamp duty and registration. The rate of stamp duty is set by the state and can differ for men, women and joint buyers.
Add parking, club membership, maintenance deposits and other one-time charges that developers often list separately. Interiors and moving costs come after that. For a buyer working to a hard ceiling of one crore, these extras can push a home over the line.
In India, a buyer also deducts TDS when paying for property above ₹50 lakh. Your accountant can explain how it works for your deal. We do not give tax advice, and rules can change.
The safest habit is to ask for a full written cost sheet that shows every line, then add your own interior and loan costs on top.
If DLF is your goal, a clear plan matters more than a hopeful one.
Use the nearest known figure as a guide, not as a promise. Ask us for the current cost sheet so your target is real.
Banks lend only part of the price, so you pay the rest. Keep the margin for taxes and fees separate from this.
Hold several months of EMIs and household costs aside. A purchase should not drain every rupee you own.
Under-construction homes often use payment plans linked to progress. Ask how much is due at booking and how much later.
Prices, rates and your savings all change. Revisit the plan and tell us if your budget moves.
Resale is the usual way a buyer gets in at a lower price than a new launch. An owner may sell an older DLF home in a different location for less. We have no verified resale listing to show on this page, so we will not guess a price.
If you try resale, do the same checks you would for a new home. Confirm that the seller owns a clear title, ask for the RERA details where they apply, and check dues, society charges and the transfer steps with the developer.
To be ready for a new launch, send us your budget, city and home type. We keep your request on file. If DLF reports a project in your range, you hear from us.
When people search for DLF projects under 1 crore, they usually want a small, easy-to-afford home. DLF's compact range is small right now. The smallest residential units in its current launches are 3 BHK floors of roughly 1,442 to 1,615 sq ft, plus larger homes elsewhere.
Smaller tickets do exist in other forms. Plots can have a smaller land size than a flat, and a shop can have a modest area. But the DLF plots and shops we track also start above one crore on the figures we have, or have no published price at all.
So the real choices are three. Raise the budget, wait for a launch in a lower band, or look at resale. We can help you with each one, and we will tell you plainly if a route is closed.
A new launch lets you pay in stages and gives you a fresh home, but the first price is high and possession is years away. A resale home may cost less per sq ft and can be used sooner, but you must check the seller's papers with care.
For a buyer near one crore, resale usually gives more room to negotiate. For a buyer who can stretch, a new launch gives the benefit of staged payments. Neither is better in every case. It depends on your savings, your timeline and your comfort with risk.
Run through these points before you give any token money.
A buyer with a firm ceiling of one crore may do better to look beyond DLF for now. The reason is not about quality. It is that the numbers do not line up, and forcing a match can lead to too much debt.
A buyer who can raise the budget to the ₹1.7 to ₹2 crore range, with a stable income and a good down payment, has a real choice to consider. A 3 BHK floor in a planned township is a solid family home if the paperwork is clear.
An investor with one crore may prefer to wait, build the amount, and enter a later launch. A small amount spent on a poor-fit property is worse than patience.
Whichever group you are in, ask us. We will give you a frank view of what is real, what is old data, and what is simply not available.
Share your budget and city. We will check for new launches, resale leads and the closest DLF options, and call you back during working hours.